Under IRS Section 121, homeowners can exclude up to $250,000 of profit from capital gains tax if filing single, or up to $500,000 if married filing jointly, provided they owned and lived in the home as their primary residence for at least two of the last five years. In Orange County, where long-term homeowners routinely see gains exceeding $800,000, profit above this threshold is exposed to both federal capital gains tax (up to 20%) and California state income tax (up to 13.3%), making adjusted basis calculations essential.
For long-time homeowners in Orange, Villa Park, North Tustin, and Santa Ana, deciding to sell is rarely a question of buyer demand—it is a question of how much equity will be lost to state and federal capital gains taxes. The federal primary residence exclusion under Internal Revenue Code § 121 was established in 1997 at $250,000 for single filers and $500,000 for married couples filing jointly. Because these limits were never indexed to inflation, three decades of appreciation have pushed typical Central Orange County equity gains far past what the law originally shielded. Calculating your real walkaway proceeds requires isolating three critical factors: your adjusted cost basis, your California marginal tax bracket, and your state withholding elections under California Form 593.
Capital Gains Fast-Track: Profit exceeding the $250,000/$500,000 Section 121 exclusion is taxed federally at up to 20%, plus the 3.8% Net Investment Income Tax (NIIT), and taxed by California as ordinary income up to 13.3%—creating a top combined marginal tax rate of 37.1%. Documenting capital improvements (additions, roofs, pools, HVAC) increases your adjusted basis dollar-for-dollar, shielding thousands from taxation. At closing, California Form 593 defaults to withholding 3.33% of the gross sales price unless you elect the Alternative Withholding Calculation.
Written by Diego Magdaleno, REALTOR® (CA DRE #01952035), Diego & Nauz | 1Vision Real Estate · Reviewed by Nauz Magdaleno, J.D. · Updated November 2026
Fiduciary financial guidance examining IRC § 121 primary exclusions, California Franchise Tax Board Form 593 withholding rules, and adjusted basis reconstruction.
Concerned About Capital Gains Taxes on Your Sale?
Consult directly with Diego Magdaleno to calculate your property's net proceeds, audit capital improvement deductions, and structure an accurate Form 593 withholding strategy.
1. How the $250,000 and $500,000 Section 121 Exclusion Actually Works
Under Internal Revenue Code Section 121, a single taxpayer can exclude up to $250,000 of capital gain from the sale of their principal residence, while a married couple filing jointly can exclude up to $500,000.
To qualify for this exclusion, you must satisfy two strict statutory tests during the 5-year period leading up to the date of sale:
- The Ownership Test: You must have owned the property for at least two full years (730 days) within the 5-year window. For married couples filing jointly, only one spouse needs to satisfy the ownership requirement.
- The Use Test: You must have lived in the home as your principal residence for at least two years within that same 5-year period. For married couples claiming the full $500,000, both spouses must independently meet the 2-year use requirement.
- The 2-Year Frequency Cap: You cannot have claimed the Section 121 exclusion on the sale of another principal residence within the two years preceding the closing date.
• Original Purchase Price (1998): $285,000
• Gross Sale Price (Today): $1,150,000
• Total Gross Realized Gain: $865,000
• Less Transaction Closing Costs & Commissions: −$65,000
• Net Realized Gain: $800,000
• Less Maximum Married Section 121 Exclusion: −$500,000
• Net Taxable Capital Gain: $300,000
Even after applying the maximum $500,000 married exclusion, this couple faces $300,000 in fully taxable capital gain. To see how total closing costs affect your starting point, review our complete breakdown of Orange County seller net proceeds & closing costs.
2. What Gain Above the Exclusion Costs a California Seller (The 37.1% Max Rate)
The most dangerous misconception among California home sellers is assuming that all capital gains are taxed at the federal 15% or 20% rate.
California does not have a preferential long-term capital gains tax rate. The California Franchise Tax Board (FTB) taxes capital gains as 100% ordinary state income. When federal surcharges are added, sellers in upper tax brackets face a combined top marginal tax rate of 37.1%:
| Tax Component | Maximum Rate | Statutory Threshold / Applicability |
|---|---|---|
| Federal Long-Term Capital Gains | 20.0% | Applies to taxable income above federal threshold ($583,750 married / $518,900 single). |
| Net Investment Income Tax (NIIT) | 3.8% | Applies to investment gain when Modified AGI exceeds $250,000 (joint) or $200,000 (single). |
| California Ordinary Income Tax | 12.3% | State income tax on California-source capital gains (sliding scale 9.3% to 12.3%). |
| CA Mental Health Surcharge | 1.0% | Mandatory 1% surcharge on total California taxable income exceeding $1,000,000. |
| Top Combined Marginal Tax Rate | 37.1% | Applies to the highest tier of un-shielded capital gains. |
In our Santiago Hills example, taxing $300,000 of excess gain at the highest combined rate results in roughly $111,300 owed in capital gains taxes. Even in moderate brackets, total state and federal tax exposure routinely lands between 28% and 33%.
The Out-of-State Relocation Myth: Moving your physical residency to Texas, Nevada, or Florida before closing escrow does not eliminate California tax. Under California Revenue and Taxation Code § 17951, real estate gains are strictly sourced to the state where the physical land is located. The Franchise Tax Board taxes 100% of the gain regardless of where you file your return.
3. Why Forensic Cost Basis Reconstruction Saves Tens of Thousands in Cash
Your capital gains tax liability is not calculated from your original purchase price—it is calculated from your adjusted cost basis.
Every single dollar of documented capital improvements increases your tax basis and decreases your taxable gain dollar-for-dollar.
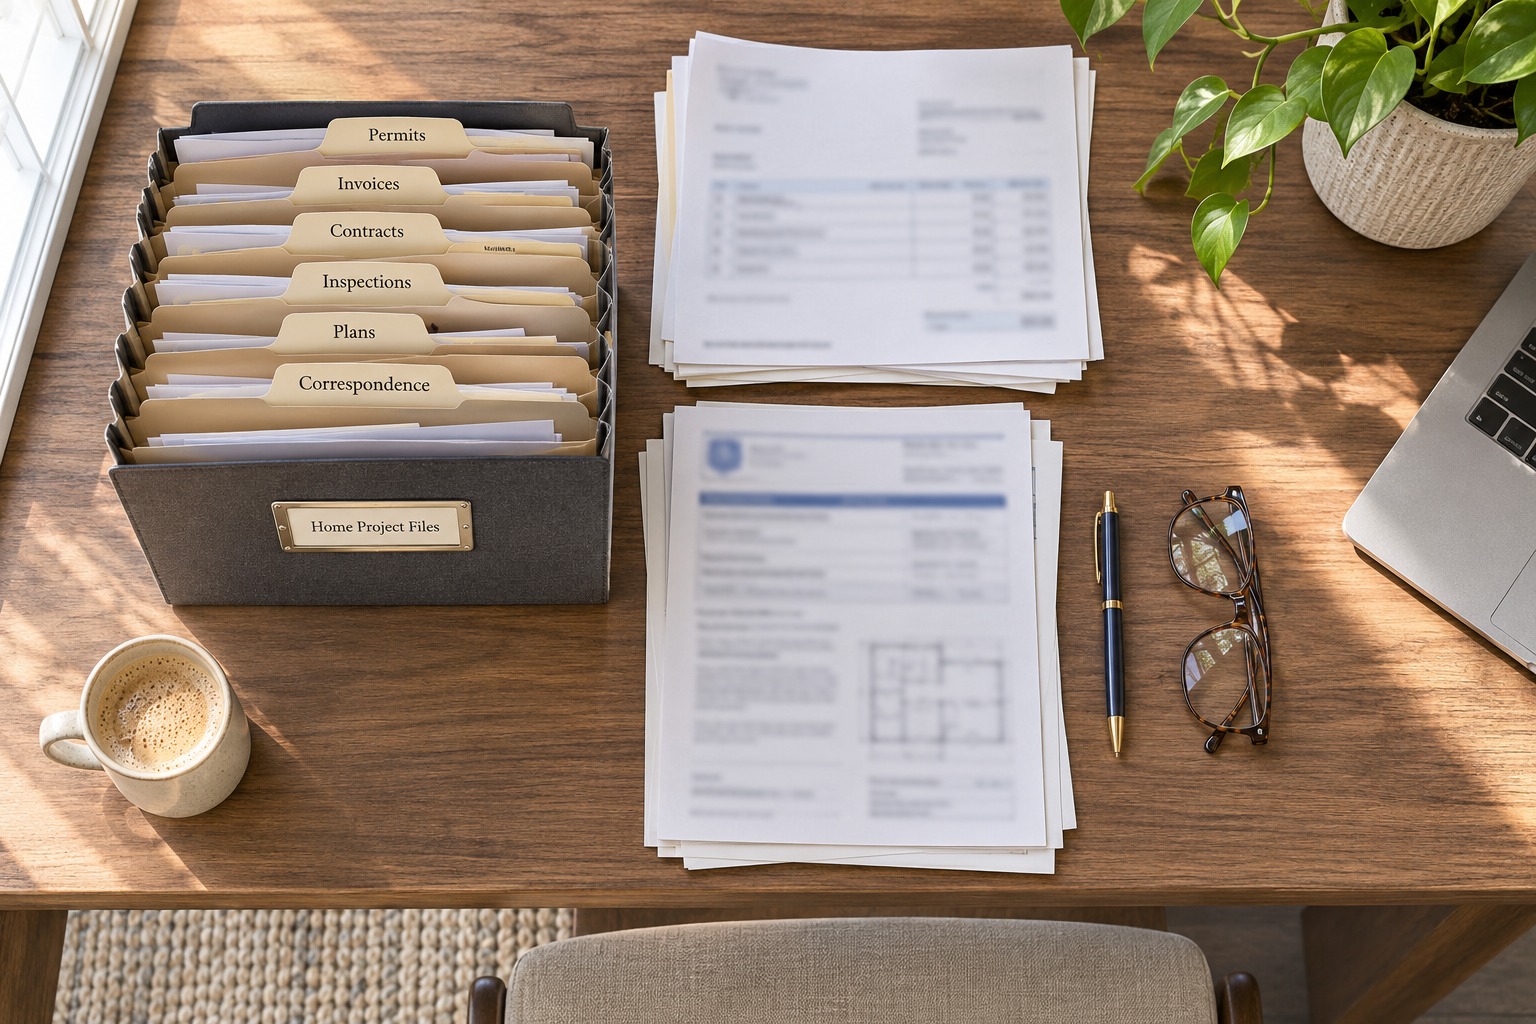
To withstand IRS and FTB audit scrutiny, improvements must be distinguished from routine maintenance:
- Qualifying Capital Additions (Increases Basis): Permanent improvements that add value, prolong the property's useful life, or adapt it to new uses: room additions, full kitchen or bath remodels, complete roof replacements, swimming pool installations, repiping from galvanized to copper/PEX, and major HVAC central heat and AC installations.
- Non-Qualifying Repairs (Does Not Increase Basis): Routine maintenance that maintains the home in ordinary operating condition: repairing a broken window, fixing a plumbing leak, repainting interior walls, or servicing a water heater.
- The Financial Impact of Forensic Accounting: If an owner who lived in a North Tustin home for 25 years conducts a forensic audit of permits, bank statements, and contractor invoices to substantiate $150,000 in capital improvements, they reduce their taxable gain by $150,000. At the 37.1% top marginal rate, that forensic documentation saves $55,650 in hard cash.
If you inherited the residence, the basis rules change entirely. Read our detailed guide on the step-up in basis on inherited Orange County homes.
Get a line-by-line estimate of county transfer taxes, Mello-Roos prorations and expected closing credits, built from recent 30-day comparable sales near your home.
4. The California Form 593 3.33% Withholding Trap at Escrow Closing
The greatest settlement surprise for Orange County home sellers is California Franchise Tax Board Form 593 (Real Estate Withholding Statement).
Under California law, escrow officers are legally mandated to withhold 3⅓% (3.33%) of the GROSS sales price and wire those funds directly to the FTB at closing unless the seller certifies an exemption or files an alternative calculation.
Case Study: The Form 593 Down Payment Shortfall
A married couple sells a North Tustin property for $2,200,000 with an outstanding mortgage balance of $1,650,000. They plan to use their remaining equity ($550,000 gross) to put $500,000 down on a replacement home in Villa Park closing on the same afternoon.
- Default 3.33% Withholding Applied: 3.33% of $2,200,000 = $73,260 withheld by escrow.
- Brokerage & Closing Costs: Deducts roughly $115,000.
- Net Cash Received at Closing: Drops to roughly $361,740.
- The Result: The couple faces a $138,260 cash shortage at the purchase escrow, jeopardizing their concurrent closing.
How to Avoid the Trap: If your net capital gain is entirely exempt under Section 121, you check Box 14 on Form 593 to claim complete exemption. If you have taxable gain exceeding $500,000, have your CPA complete Part IV (the Alternative Withholding Calculation) before closing. This bases withholding on your actual estimated gain and state bracket rather than an arbitrary 3.33% deduction from gross sales proceeds.
If you are timing a sale and purchase together, study our guide on buying and selling a home at the same time in Orange County and the Orange County escrow timeline.
Need a Professional Net Sheet and Basis Audit?
1Vision coordinates directly with your CPA or estate tax attorney—modeling exact walkaway proceeds, calculating Form 593 alternative withholding, and verifying Section 121 qualifications.
5. Strategies for Sellers Facing Substantial Gains Above the Exclusion
When home appreciation substantially exceeds the $500,000 cap, sellers generally evaluate four distinct structural paths:
- 1. Outright Sale & Tax Satisfaction: The cleanest path. You claim your $250k or $500k exclusion, pay the state and federal tax on the remainder, and walk away with liquid capital. For downsizers funding care or moving into a smaller home, simplicity and liquidity often outweigh tax deferral overhead.
- 2. Installment Sale (IRC § 453 Seller Financing): By carrying a promissory note for a qualified buyer, you recognize capital gain proportionally over several tax years as principal is repaid. This can prevent a massive one-time gain from pushing you into California's top 13.3% tax bracket or triggering the 1% Mental Health surcharge. Note that depreciation recapture cannot be deferred under an installment sale.
- 3. Combining Section 121 with a Section 1031 Exchange (IRS Rev. Proc. 2005-14): If you convert your primary residence into an active rental property for a bona fide investment period (typically 12 to 24 months), you can exclude gain up to $500,000 tax-free under Section 121 and defer the remaining taxable profit into replacement investment real estate under Section 1031.
- 4. Proposition 19 Property Tax Portability: While Proposition 19 does not eliminate income capital gains tax, it protects qualifying homeowners aged 55+, severely disabled, or wildfire victims by allowing them to transfer their low Proposition 13 base year property tax value to any replacement primary residence in California up to three times. Study our roadmaps in the Prop 19 base-year transfer guide and Prop 19 sell timing in Orange County.
6. Special Circumstances: Surviving Spouses, Assisted Living, and Prior Rentals
Specific statutory exceptions adjust the 2-out-of-5-year rule for life transitions:
- Surviving Spouses (The 2-Year Window under IRC § 121(b)(4)): An unmarried surviving spouse can claim the full $500,000 married exclusion if the sale closes within two years of the date of death, provided the ownership and use tests were satisfied prior to the spouse's passing. If the closing slips past that 2-year window, the exclusion drops to the single limit of $250,000.
- Licensed Care Facility Exception (IRC § 121(d)(7)): If a homeowner becomes physically or mentally incapable of self-care, the required use test drops from two years to just one full year of residence during the 5-year lookback. All subsequent time spent residing in a state-licensed facility (assisted living or memory care) counts as residence in the home. Read our guide on whether to sell a home to pay for assisted living in Orange County.
- Prior Rental / Nonqualified Use Rules: If a property was used as a rental property prior to being occupied as a primary residence, the Housing and Economic Recovery Act (HERA) of 2008 mandates that gain attributable to periods of nonqualified use after 2008 cannot be excluded under Section 121 and is subject to proportional taxation.
- Historic Properties & Mills Act Contracts: In Old Towne Orange, character homes frequently carry active Mills Act contracts. While Mills Act property tax savings run with the land, unpermitted alterations can trigger title clouds. Review our guide to historic homes in Old Towne Orange.
7. Should You Sell Now or Wait? The Fiduciary Decision Framework
Because Section 121 limits ($250,000 and $500,000) are un-indexed to inflation, waiting for property values to appreciate further usually increases your tax burden. Every dollar of future appreciation above the cap is fully taxable at combined state and federal rates up to 37.1%. For a recent South County sale, see our Laguna Niguel case study.
Follow this 6-step sequence to determine whether to list:
- Calculate your true adjusted basis: original purchase price plus documented capital improvements and un-deducted closing purchase fees.
- Deduct estimated sales commissions, title fees, escrow costs, and transfer taxes ($1.10/$1,000) from your estimated sales price.
- Compare your net profit against your $250,000 (single) or $500,000 (married) Section 121 exclusion limit.
- Have your CPA model federal capital gains, NIIT, and California ordinary tax on the remaining gain based on your specific annual income bracket.
- Work with your escrow officer to complete Form 593 Part IV (Alternative Withholding Calculation) to avoid the default 3.33% gross withholding penalty.
- If eligible for Proposition 19, synchronize your sale and replacement purchase to preserve your low property tax base.
8. Frequently Asked Questions
Do I have to buy another home to avoid capital gains tax in California?
No. The old federal "rollover rule" that required purchasing a replacement home of equal or greater value was repealed in 1997. Under IRC Section 121, as long as you meet the 2-out-of-5-year ownership and use tests, you can take your excluded gain ($250,000 single / $500,000 married) in 100% cash with zero obligation to reinvest in real estate.
Does California have a lower long-term capital gains tax rate?
No. California does not offer preferential tax rates for long-term capital gains. The California Franchise Tax Board taxes all real estate capital gains as ordinary income at your applicable state income tax rate (up to 12.3%, plus a mandatory 1% Mental Health Services surcharge on taxable income over $1,000,000).
What capital improvements increase my home's cost basis?
Permanent capital additions that add value, prolong useful life, or adapt the home to new uses increase your basis: room additions, full kitchen or bath remodels, roof replacements, swimming pools, upgraded electrical panels, repiping, and new HVAC systems. Routine repairs and maintenance (painting, fixing leaks, minor repairs) do not qualify.
What is California Form 593 real estate withholding?
California Form 593 requires escrow to withhold 3.33% of the gross sales price at closing and remit it to the Franchise Tax Board as estimated state tax. Sellers can avoid or reduce this withholding by certifying a full primary residence exemption or electing the Alternative Withholding Calculation based on actual gain.
How does a surviving spouse qualify for the $500,000 exclusion?
Under IRC Section 121(b)(4), an unmarried surviving spouse can claim the full $500,000 married exclusion if the property is sold within two years of the deceased spouse's date of death, provided the ownership and use tests were met prior to death. After two years, the exclusion drops to the single filer limit of $250,000.
Plan Your Orange County Sale With Trusted Local Specialists
Diego Magdaleno has successfully closed over 460 residential transactions across Central Orange County since 2012. Supported by Nauz Magdaleno, JD, the 1Vision team provides strategic net proceeds modeling, basis audit support, and fiduciary representation across Orange, Villa Park, North Tustin, and Santa Ana.
Diego Magdaleno · CA DRE# 01952035 | 1Vision Real Estate · CA DRE# 02051216
Headquarters: 625 The City Drive S, Suite 400, Orange, CA 92868
Book a Confidential Equity & Tax Strategy Call with Diego
Select a convenient date and time to review your home's valuation, examine estimated net proceeds, and prepare for your CPA consultation.