Having your home insured through the California FAIR Plan does not prevent you from selling your Orange County property, and Fannie Mae lending guidelines explicitly permit FAIR Plan coverage on financed transactions. However, a buyer cannot close a conventional mortgage on a base FAIR Plan dwelling policy alone. Following the California Department of Insurance's approval of a 29.1% statewide average FAIR Plan rate increase effective October 15, 2026, underwriting scrutiny and buyer Debt-to-Income (DTI) friction have intensified across foothill communities like Villa Park, North Tustin, Anaheim Hills, and Orange Park Acres. Closing smoothly requires preparing your property's defensible space, roof documentation, and rebuild valuation before the first showing.
Selling an Orange County home insured through the California FAIR Plan requires packaging binding insurance quotes before listing on the MLS. Following the October 15, 2026 statewide 29.1% FAIR Plan rate increase and its $3 million residential dwelling coverage cap, buyers can cancel escrow during their 17-day investigation period when surprised by combined FAIR Plan and Difference in Conditions (DIC) premiums. Securing pre-listing quotes and completing the required AB 38 defensible space disclosures (for homes in High or Very High Fire Hazard Severity Zones) prevents insurance contingencies from collapsing your sale.
Written by Diego Magdaleno, REALTOR® (CA DRE #01952035), Diego & Nauz | 1Vision Real Estate · Reviewed by Nauz Magdaleno, J.D. · Updated November 2026
Fiduciary real estate analysis examining California FAIR Plan October 2026 rate adjustments, Fannie Mae DIC underwriting rules, AB 38 fire inspections, and $3M coverage caps.
Preparing to Sell a Foothill or High-Fire-Zone Home?
Consult directly with Diego Magdaleno to verify your AB 38 inspection jurisdiction, pre-audit buyer DTI insurance impacts, and connect with specialized surplus-lines brokers.
1. Can You Sell an Orange County Home Insured by the California FAIR Plan?
Yes. Being insured through California’s insurer of last resort does not restrict your legal right to sell, and Fannie Mae and Freddie Mac guidelines permit FAIR Plan coverage on financed transactions. However, escrows fail when buyers assume a standard insurance binder can be placed in 48 hours during Week 3 of escrow.
Two operational realities govern every FAIR Plan transaction:
- Policies Do Not Transfer: Your existing FAIR Plan coverage cannot be assigned to the incoming buyer. Every buyer must underwrite and bind a brand-new policy effective on the exact date of closing.
- Base Policies Fail Lender Rules: A standard FAIR Plan policy covers only basic named perils (fire, lightning, smoke, and internal explosion) and settles claims at depreciated Actual Cash Value (ACV). Financed buyers must pair it with specific endorsements and a wraparound policy to clear mortgage underwriting.
2. What Changed With FAIR Plan Rates in October 2026 (The 29.1% Hike)?
Effective October 15, 2026, the California Department of Insurance approved a 29.1% statewide average rate increase for FAIR Plan residential dwelling policies. Because wildfire exposure drives the largest component of the rate formula, foothill properties in Orange County frequently see premium adjustments exceeding the statewide average.
The Buyer Debt-to-Income (DTI) Squeeze: Mortgage underwriters qualify buyers based on total monthly housing expense (PITI + HOA + Special Taxes), not simply the purchase price. When an insurance quote jumps from $4,500/year to $10,500+/year ($875/month), that extra $500/month in carrying cost reduces a buyer's maximum mortgage borrowing power by roughly $75,000.
Additionally, because the FAIR Plan reduced agent commission structures, many general captive insurance agents decline to process FAIR Plan applications. Sellers should require buyers' lenders to verify insurance quotes using specialized independent wildfire brokers during the first week of escrow.
3. What Lenders Require: Replacement Cost Endorsements & DIC Wrap Policies
For 1-to-4 unit residential properties, Fannie Mae property insurance rules mandate "Special Form" (all-risk) coverage, Replacement Cost Value (RCV) settlement, and a maximum deductible no higher than 5% of the dwelling limit. To meet these requirements, buyers must assemble a two-policy structure:
- 1. FAIR Plan Dwelling Policy + Replacement Cost Endorsement: Covers catastrophic fire and smoke damage. Adding the mandatory Replacement Cost Value (RCV) endorsement typically increases the base FAIR Plan premium by 15% to 25%.
- 2. Difference in Conditions (DIC) Companion Policy: Issued by a private insurance carrier to cover everything the FAIR Plan omits—including burst-pipe water damage, theft, windstorm, and personal liability. A DIC wrap typically costs an additional 25% to 60%+ of the base FAIR Plan premium.
Review how insurance contingencies align with loan approvals in our Orange County escrow timeline guide.
4. Which Fire Agency Handles Your AB 38 Defensible Space Inspection?
Under California Civil Code Section 1102.19 (AB 38), sellers of properties located in designated High or Very High Fire Hazard Severity Zones (updated by CAL FIRE Local Responsibility Area maps) must deliver written documentation proving the property passed a defensible space inspection within the trailing 6 months.
Routing your inspection request to the wrong fire agency wastes critical weeks:
- Orange County Fire Authority (OCFA): Inspects properties in North Tustin, Tustin, Villa Park, Anaheim Hills (contract zones), and unincorporated Orange Park Acres. OCFA point-of-sale inspections are free of charge, take roughly 30 minutes, and issue passing compliance certificates within a few business days.
- City of Orange Fire Department: Handles properties located inside incorporated City of Orange boundaries, including Santiago Hills, East Orange, El Modena, Old Towne Orange, and incorporated pockets of Orange Park Acres.
Zone 0 (The First 5 Feet) Guidance: While California’s Board of Forestry has been finalizing phased statewide regulatory implementation under AB 3074 for the 0-to-5-foot ember-resistant zone, both AB 38 inspectors and private insurance underwriters already flag combustible bark mulch, firewood stacks, and wooden gates attached directly to stucco/siding. Clearing the first five feet prior to listing protects both your AB 38 certificate and buyer insurance quotes. Study the full statutory requirements in our California seller disclosures guide.
Properties in Very High Fire Hazard Severity Zones also trigger the defensible space compliance rules under Civil Code §1102.19 (AB 38). See how those documents fit alongside the rest of your paperwork in our guide to California seller disclosure requirements.
Before you go live on the MLS, we review solar UCC-1 filings, HOA §4525 and SB 326 status, and fire-zone insurance quotes so surprises surface before escrow, not during it.
5. Pre-Listing Wildfire Retrofits: Cost vs. Underwriting Payoff
Focus capital on low-cost home-hardening upgrades that prevent insurance rejections rather than chasing minor premium discounts:
| Pre-Listing Retrofit / Repair | Typical OC Cost | Insurance & Escrow Impact |
|---|---|---|
| Zone 0 Clearing (0–5 ft Perimeter) | $0 to $600 (Labor) | Eliminates immediate AB 38 inspection flags and underwriting photo rejections. |
| 1/16-Inch Ember-Resistant Attic Vents | ~$1,100 to $2,200 | Satisfies California Safer from Wildfires home-hardening discounts. |
| Noncombustible Fence-to-House Gate | $450 to $1,600 | Replaces combustible wood fencing touching home exterior with metal/masonry. |
| Obsolete Electrical Panel Swap | $2,500 to $5,000 | Replacing Federal Pacific (FPE) or Zinsco panels removes automatic carrier declines. |
| Class A Roof Replacement / Tile Re-Lay | $14,000 to $36,000 | Necessary if composition shingle roof exceeds 15–20 years or has wood shake. |
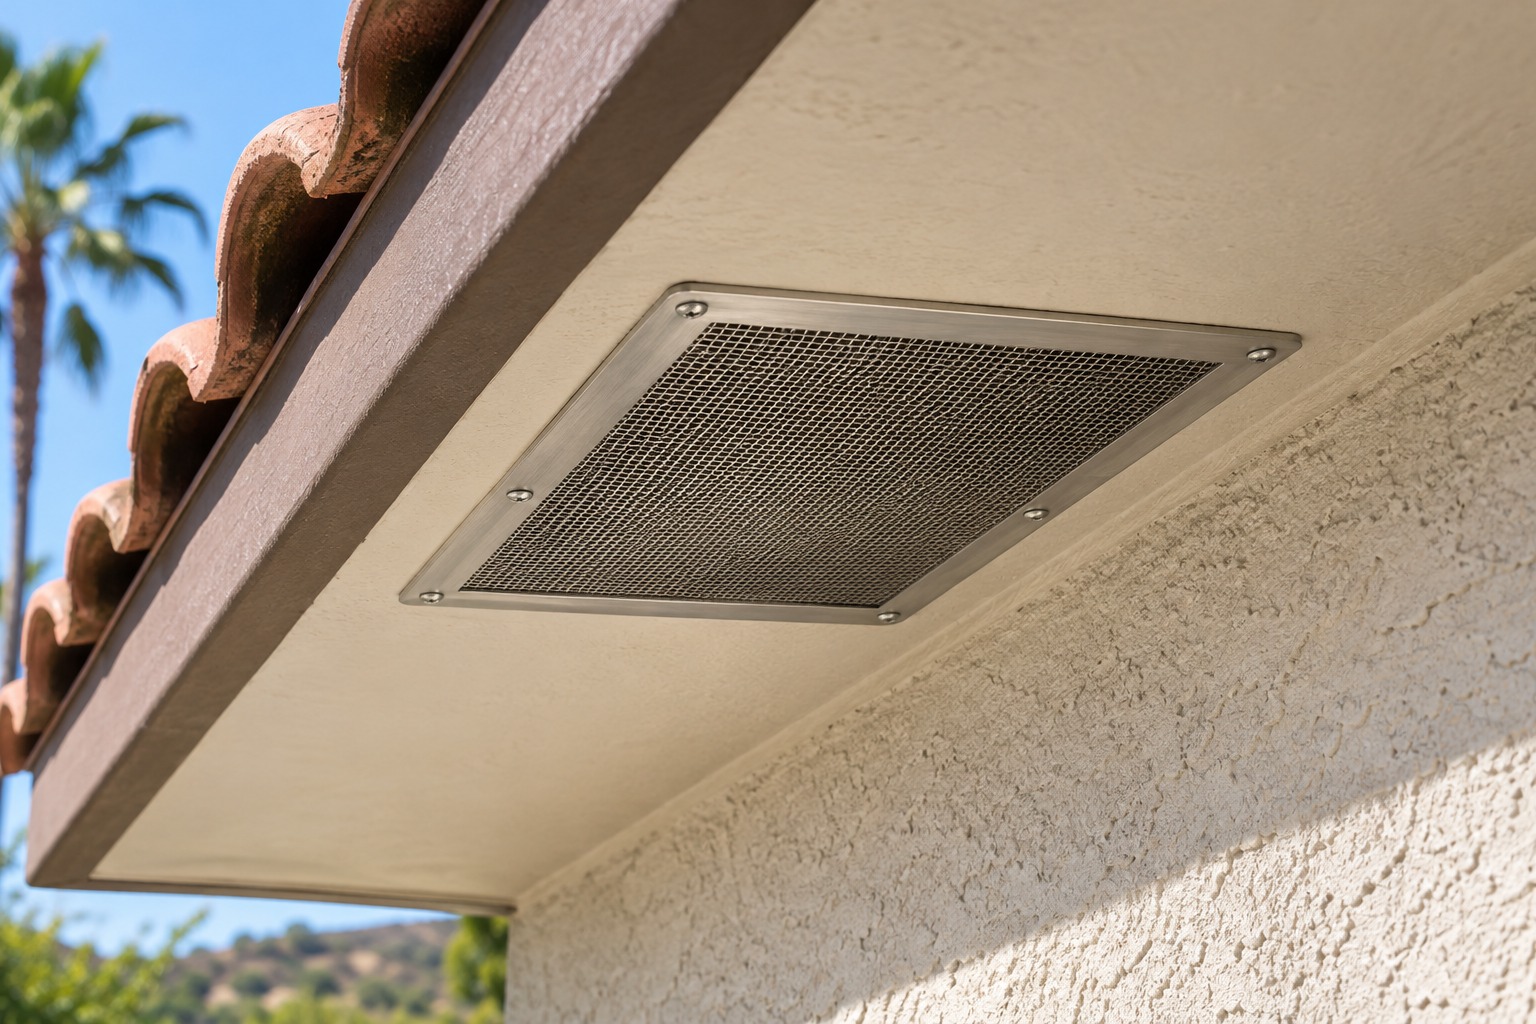
Defensible space and hardening work often becomes a negotiation line item: buyers may ask for closing credits to offset first-year premiums or brush clearance. Build those concessions into your Orange County seller net proceeds math before you set a price.
6. When the $3,000,000 FAIR Plan Dwelling Cap Creates a Coverage Gap
The California FAIR Plan enforces a strict residential coverage ceiling of $3,000,000 combined across the dwelling structure, other structures, personal property, and loss of use.
In luxury acreage enclaves such as Villa Park, Lemon Heights, and Orange Park Acres, custom rebuild costs frequently exceed $3,000,000. Because Fannie Mae requires insurance coverage equal to 100% of the insurable replacement cost (or the unpaid principal balance of the loan), a buyer borrowing $2,800,000 on a home with a $4,200,000 rebuild valuation faces a coverage gap that must be bridged using a secondary Excess / Surplus-Lines wrap policy.
Additionally, any FAIR Plan application requesting more than $1,500,000 in combined coverage requires four-sided exterior photographs and a formal licensed rebuild cost estimate. Gathering these documents prior to listing saves two weeks of escrow processing.
Selling a High-Value Home in a Wildfire Zone?
1Vision coordinates pre-listing rebuild estimates, surplus-lines broker referrals, and AB 38 inspections across Villa Park, North Tustin, and Orange Park Acres to prevent mid-escrow buyer cancellations.
7. How Long Escrow Takes With a FAIR Plan Policy (30–60 Day Window)
According to the California Department of Insurance, underwriting and binding a new FAIR Plan policy typically takes 30 to 60 calendar days once a complete application is submitted. Trying to force a 21-day or 30-day closing on a financed foothill sale regularly results in escrow extension demands.
Protect your closing date with four operational rules:
- Require Day-1 Insurance Applications: Instruct the buyer to submit applications simultaneously to admitted private carriers, surplus-lines brokers, and a FAIR Plan + DIC specialist within 24 hours of contract acceptance.
- Deliver Pre-Listing Documentation Upfront: Provide your passing AB 38 inspection certificate, roof permit/age records, and rebuild cost estimate on Day 1.
- Confirm Lender Approval Before Contingency Removal: Require written confirmation from the buyer's mortgage underwriter that the FAIR Plan + DIC binder satisfies loan conditions prior to Day 17.
- Maintain Coverage Until Recording: Never cancel your existing FAIR Plan policy until the escrow officer confirms the Grant Deed has officially recorded with the Orange County Clerk-Recorder.
If you are coordinating a concurrent replacement purchase, review our guide on buying and selling at the same time in Orange County.
Keep the buyer’s 17-day investigation period in mind: insurance quotes and the AB 38 report should be in hand before it starts. Our Orange County escrow timeline shows where each contingency falls.
8. How Proposition 19 and the Mills Act Interact With High-Fire Sales
Property tax portability and historic preservation rules directly influence seller net proceeds in Central Orange County:
- California Proposition 19 Portability: Homeowners aged 55 or older (or wildfire disaster victims) can transfer their low Proposition 13 base year property tax value to a replacement primary residence anywhere in California within two years of selling. Those annual property tax savings frequently offset elevated wildfire insurance premiums on a replacement home. Study our roadmaps in the Prop 19 base-year transfer guide and Prop 19 sell timing in Orange County.
- Mills Act Historic Contracts: While the City of Orange suspended new Mills Act applications in January 2026, existing recorded Mills Act contracts transfer automatically to buyers and provide substantial property tax reductions. Santa Ana's Floral Park program remains open to new applications. Review our guide to historic homes in Old Towne Orange.
9. The 90-Day Pre-Listing Action Plan for High-Fire-Zone Sellers
Follow this 6-step timeline starting 90 days before market launch:
- Verify Fire Hazard Zone & Agency: Check CAL FIRE LRA maps and confirm whether OCFA or the City of Orange Fire Department holds inspection jurisdiction.
- Assemble Policy & Roof Records: Gather your current FAIR Plan declarations, roof installation permits, and any non-renewal notices.
- Test Private Market Availability: Have an independent wildfire broker run preliminary quotes across admitted and surplus-lines carriers so buyers see viable insurance options.
- Execute High-ROI Hardening Fixes: Clear combustibles within 5 feet of the structure, install 1/16-inch ember vents, and swap obsolete electrical panels.
- Obtain Licensed Rebuild Valuation: Required upfront if dwelling replacement cost exceeds $1,500,000.
- Schedule AB 38 Inspection at Listing: Include the passing certificate in your upfront disclosure packet.
If you are liquidating a family estate, read our comprehensive guide to selling a parent's home in Orange County.
10. Frequently Asked Questions
Can a buyer get a conventional mortgage on a home insured by the California FAIR Plan?
Yes. Fannie Mae and Freddie Mac guidelines accept California FAIR Plan coverage, provided the buyer adds a Replacement Cost Value (RCV) endorsement to the FAIR Plan policy and pairs it with a supplemental Difference in Conditions (DIC) policy covering theft, water damage, and personal liability.
How much did California FAIR Plan rates increase in October 2026?
Effective October 15, 2026, the California Department of Insurance approved a 29.1% statewide average rate increase for FAIR Plan residential dwelling policies, with higher-risk wildfire foothill properties often experiencing increases above the statewide average.
What is the maximum residential coverage limit on the California FAIR Plan?
The California FAIR Plan caps residential coverage at $3,000,000 combined across the dwelling, other structures, personal property, and loss of use. Homes with rebuild costs exceeding $3,000,000 require a supplemental excess or surplus-lines wrap policy to satisfy mortgage lender requirements.
Which fire agency conducts AB 38 defensible space inspections in Central Orange County?
The Orange County Fire Authority (OCFA) conducts free point-of-sale AB 38 inspections in North Tustin, Tustin, Villa Park, and unincorporated Orange Park Acres, while the City of Orange Fire Department handles properties inside incorporated City of Orange limits (including Santiago Hills and El Modena).
How long does it take to bind a new FAIR Plan policy during escrow?
According to the California Department of Insurance, processing and binding a complete California FAIR Plan application typically takes 30 to 60 calendar days, making a 45-to-60-day escrow period advisable for financed buyers in high-fire zones.
Plan Your Orange County Sale With Trusted Local Specialists
Diego Magdaleno has successfully closed over 460 residential transactions across Central Orange County since 2012. Supported by Nauz Magdaleno, JD, the 1Vision team coordinates AB 38 defensible space inspections, surplus-lines insurance audits, and escrow timelines across Villa Park, North Tustin, Anaheim Hills, and Orange Park Acres.
Diego Magdaleno · CA DRE# 01952035 | 1Vision Real Estate · CA DRE# 02051216
Headquarters: 625 The City Drive S, Suite 400, Orange, CA 92868
Book a Confidential High-Fire-Zone Sale Strategy Call with Diego
Select a convenient date and time to review your property's insurance profile, schedule AB 38 inspections, and structure a smooth escrow timeline.